
Top 5 Takeaways from SIFMA’s Economist Roundtable End-Year Survey
- Katie Kolchin, CFA
The Fed Is Done – When Will It Cut Rates?
In our semiannual economic survey (published every June and December), we ask our SIFMA Economist Roundtable to provide their assessment of the current economic environment and potential monetary policy actions. Last week, we published our 2023 end-year survey. Here are our top five takeaways:
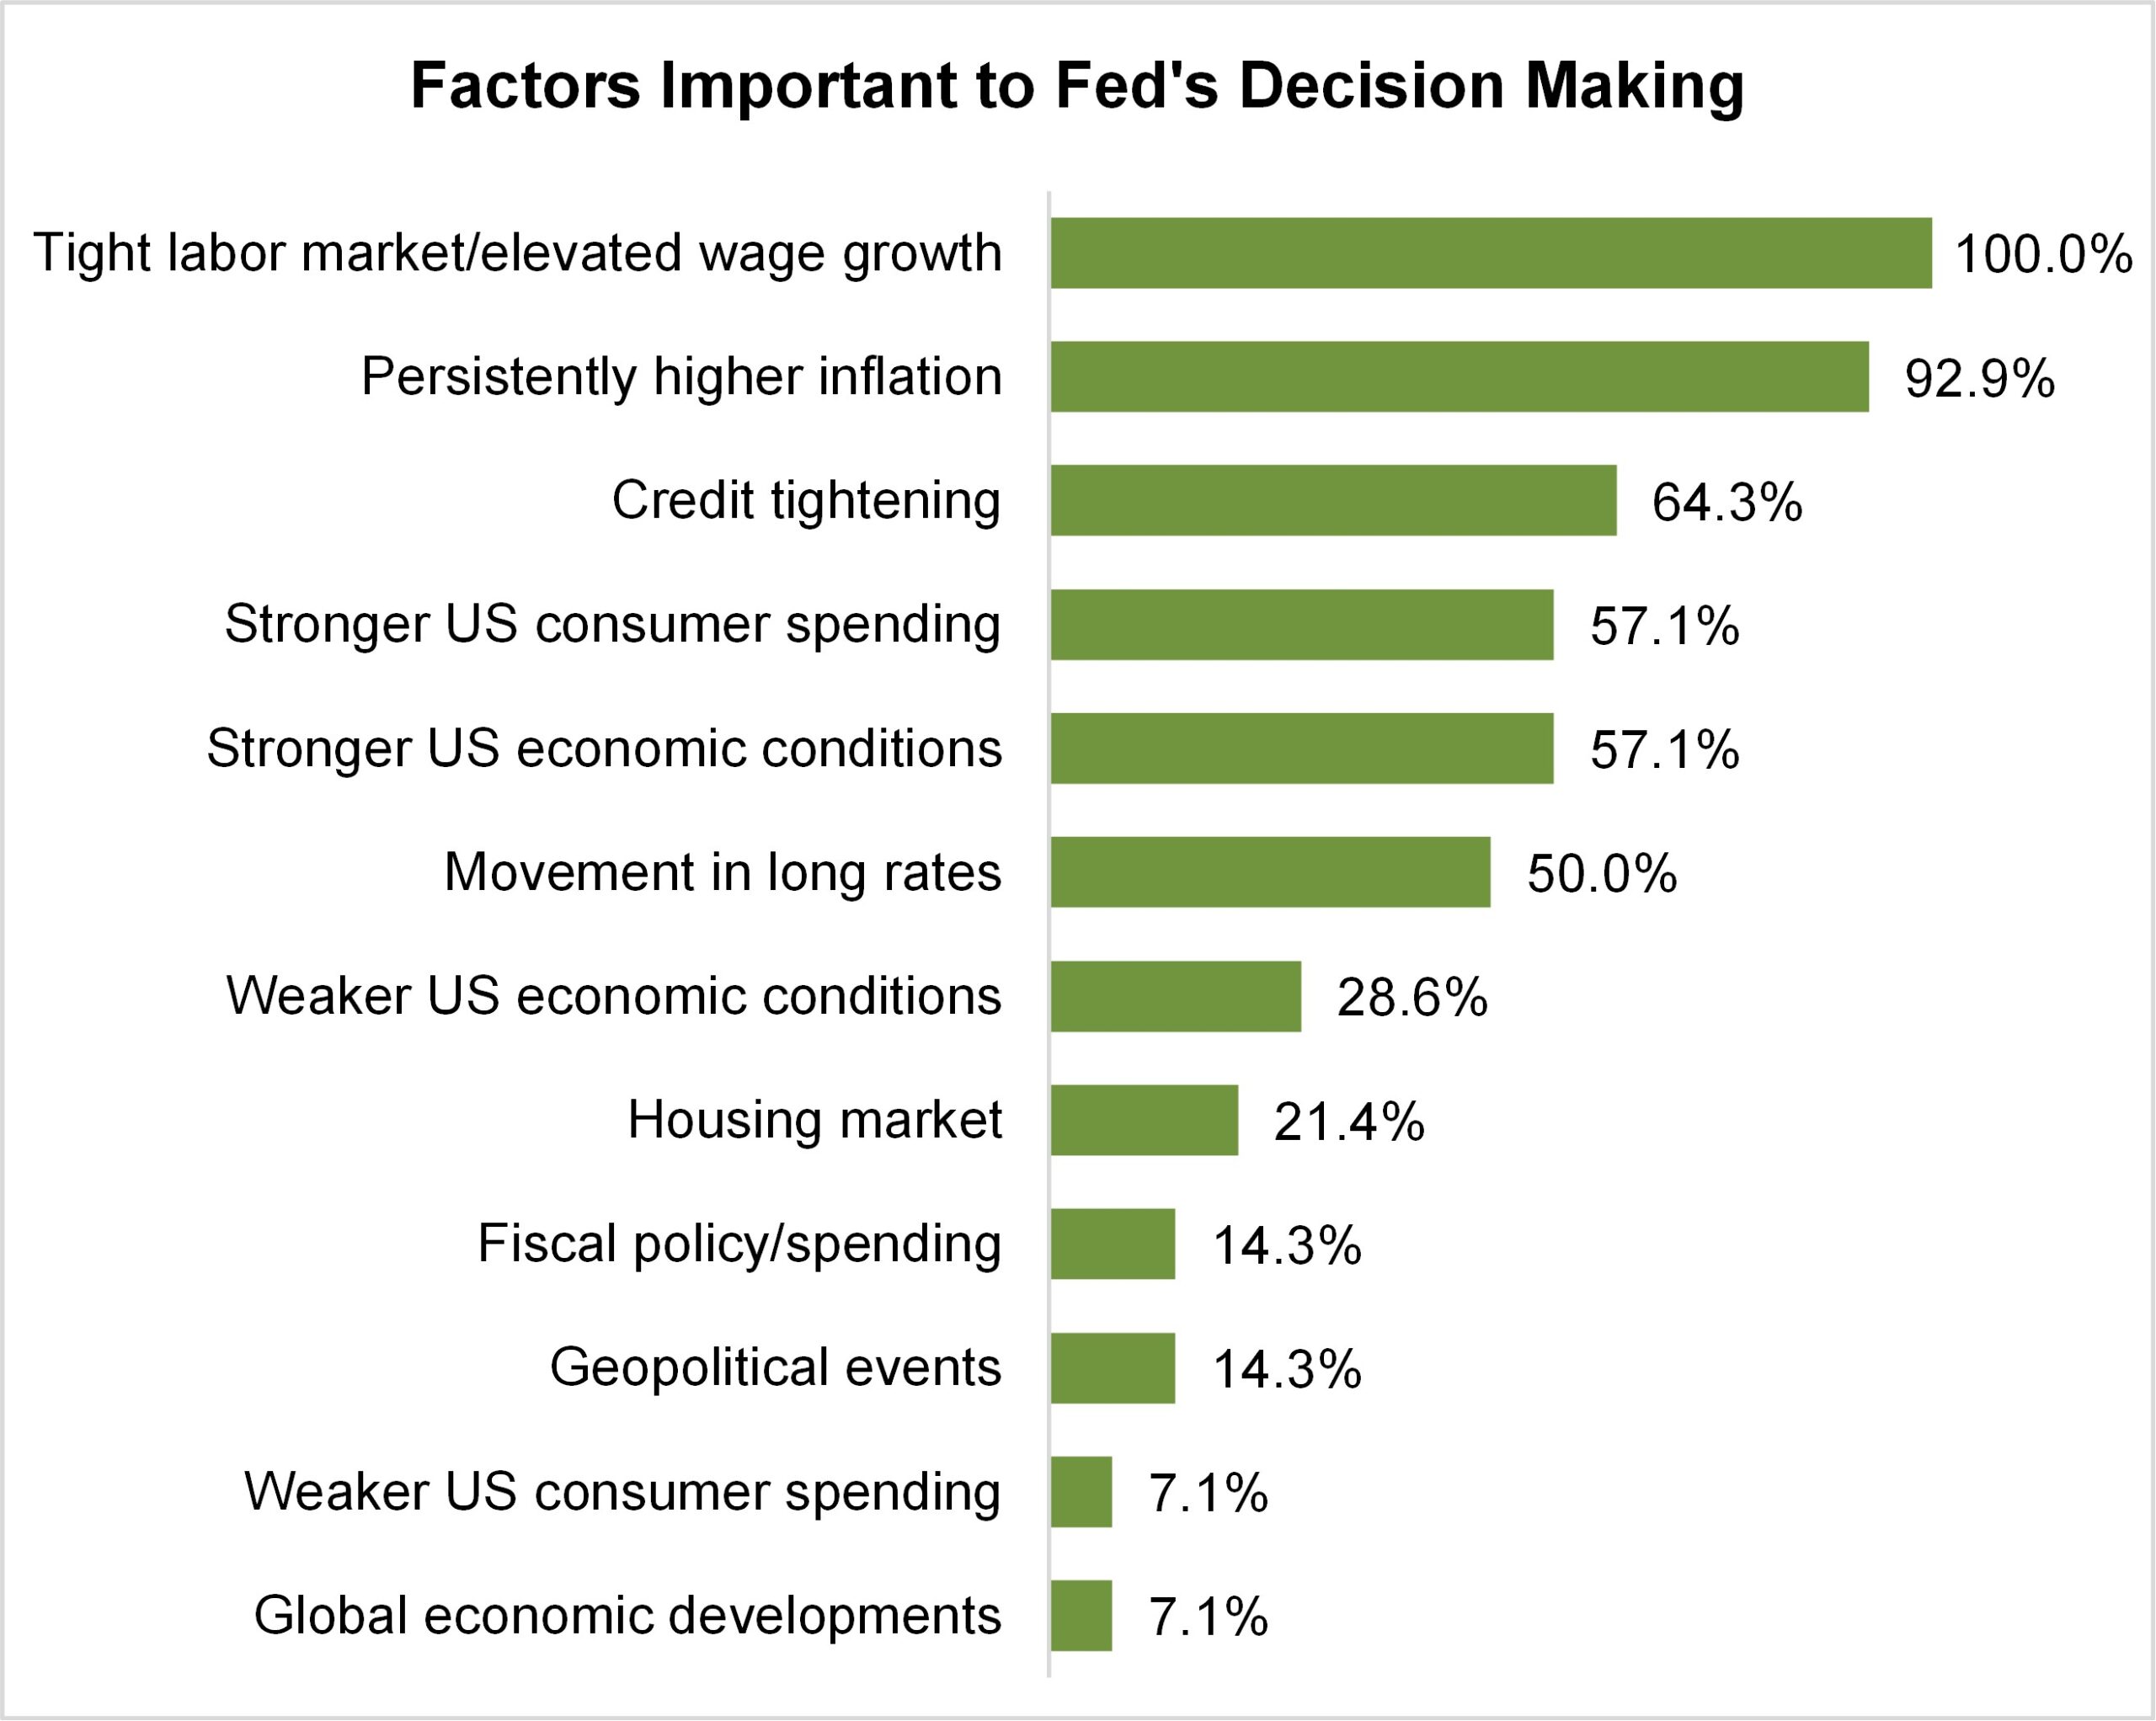
#1. A tight labor market and elevated wage growth are the most important factors in the Fed’s decision-making. Survey respondents ranked this unanimously. Coming in just behind at 92.9% of respondents is persistently higher inflation. Credit tightening followed with 64.3% of respondents.
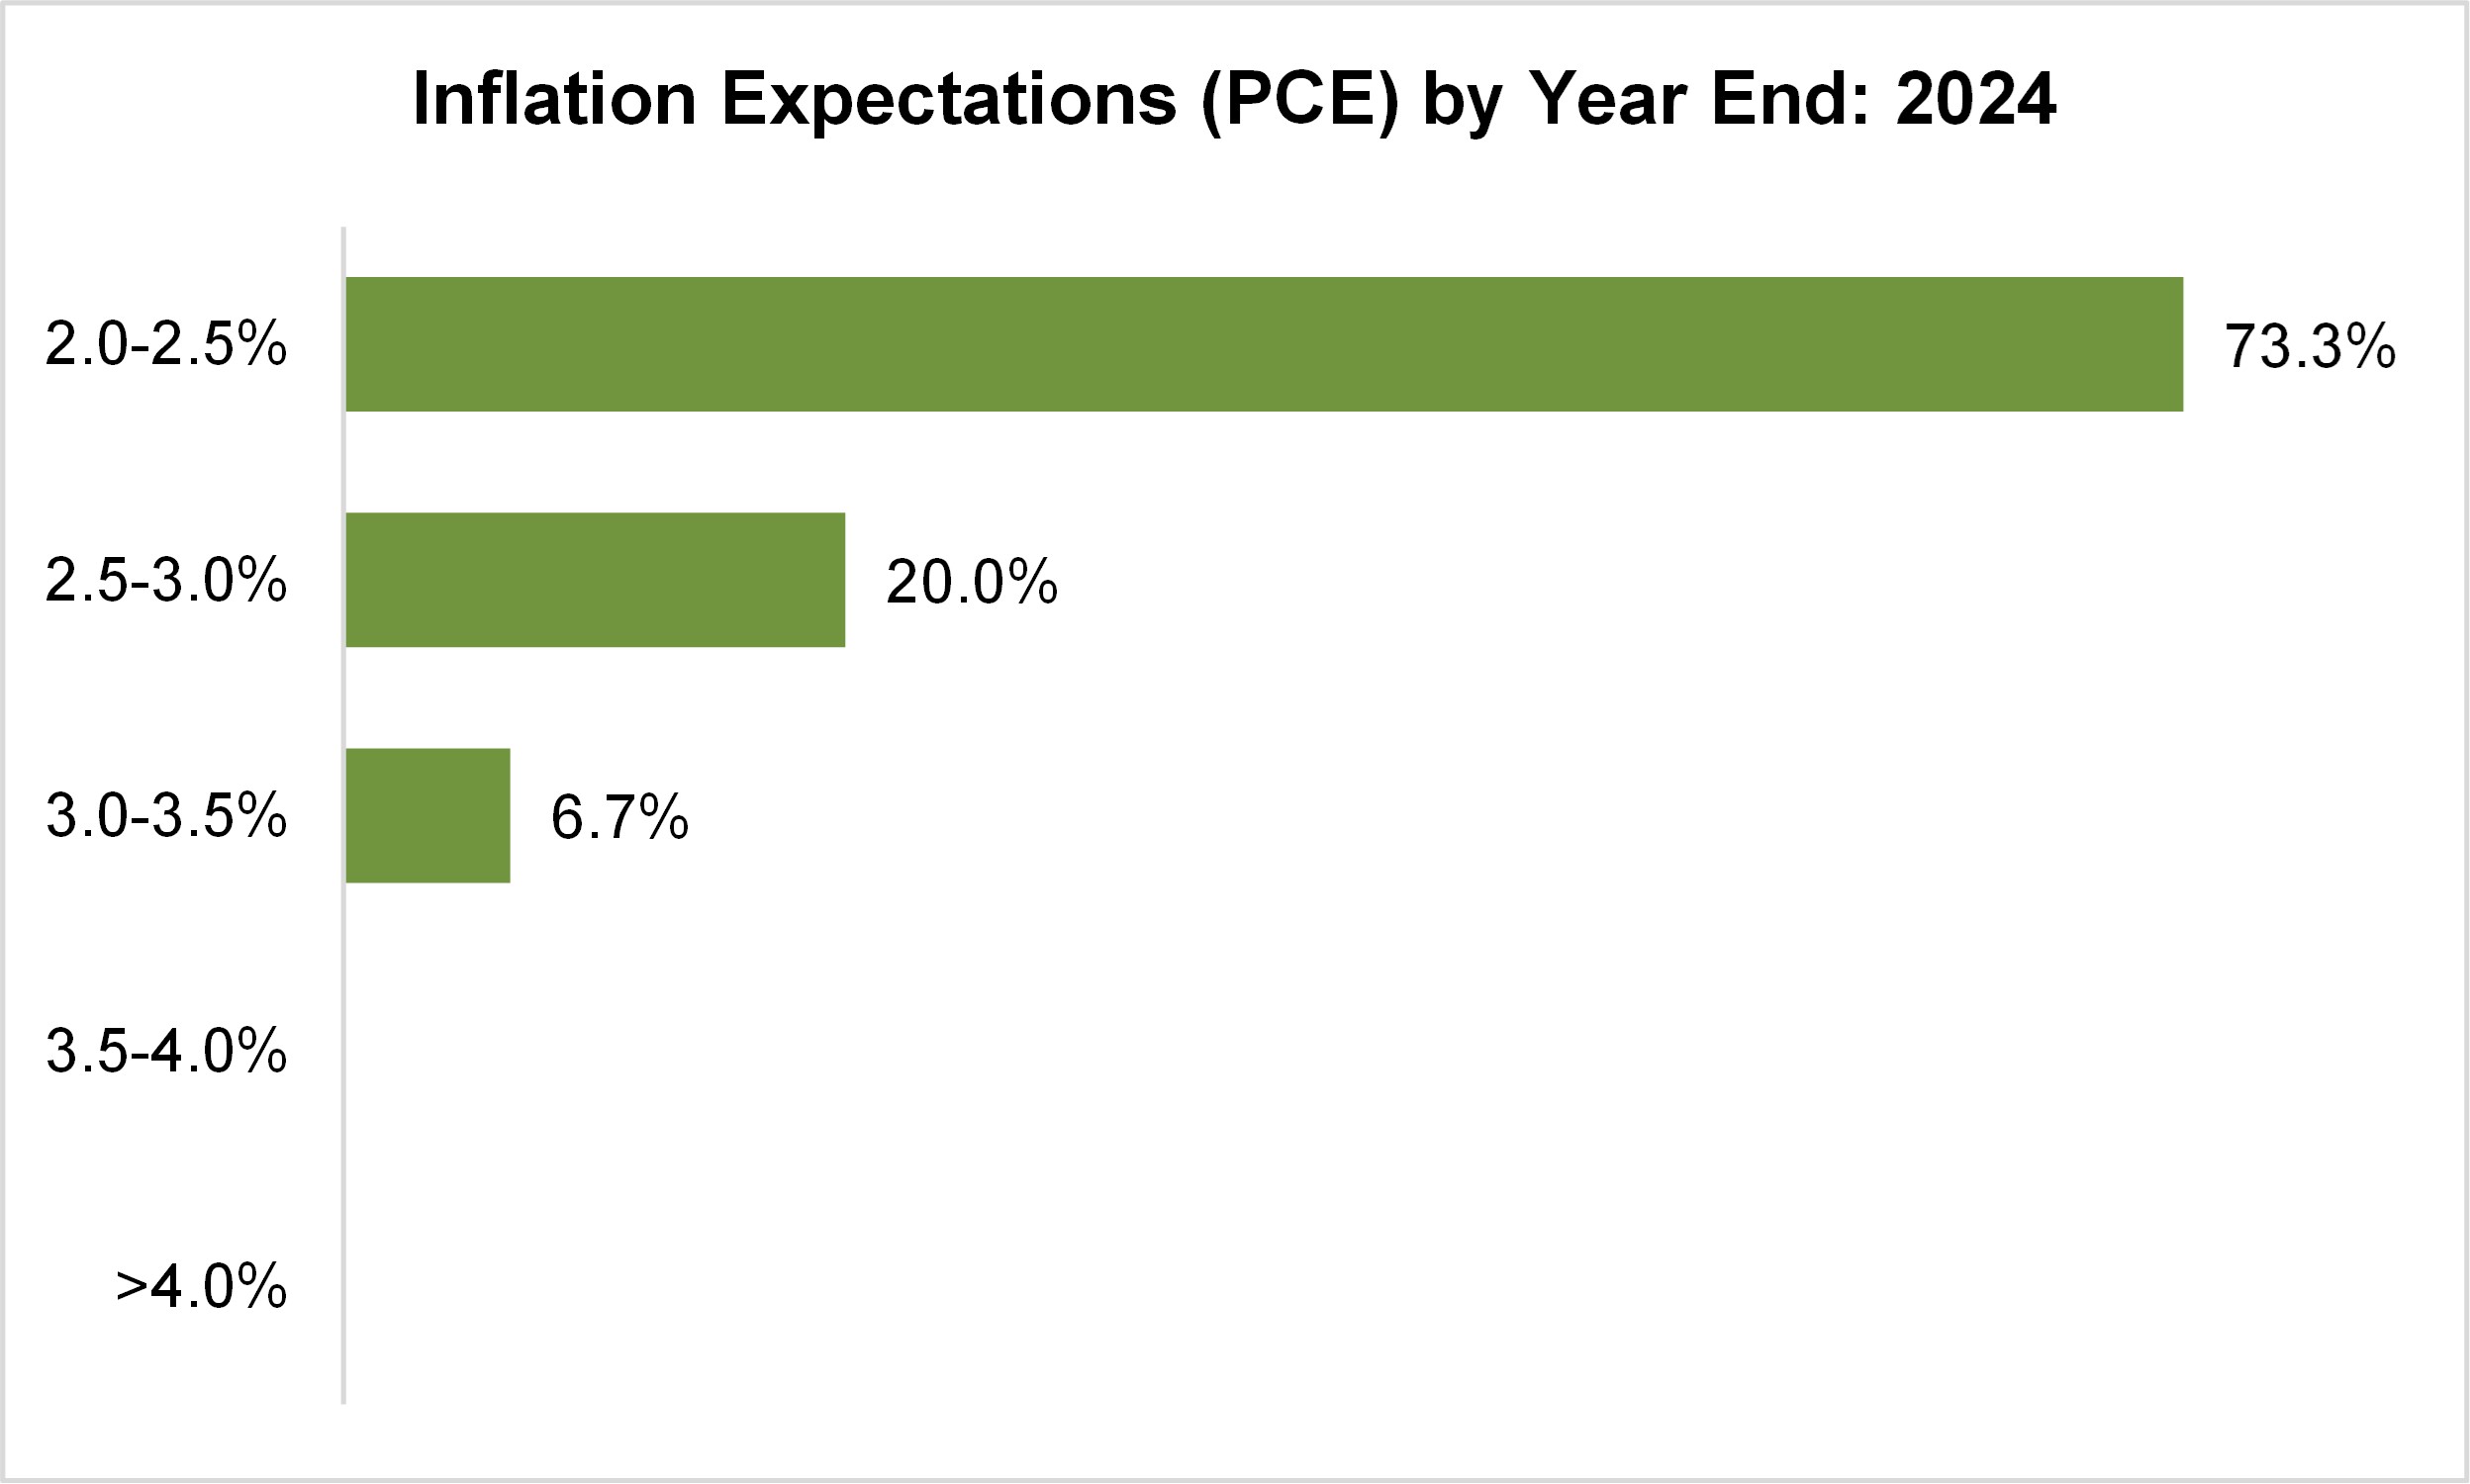
#2. We are on track to get back down to the Fed’s 2% inflation target by year-end 2024. As of October, PCE – the Fed’s preferred inflation measure – was +3.0% Y/Y. Economists expect PCE to end: 2023 at +3.0-3.5% (53.3% of respondents) and 2024 at +2.0-2.5% (73.3% of respondents).
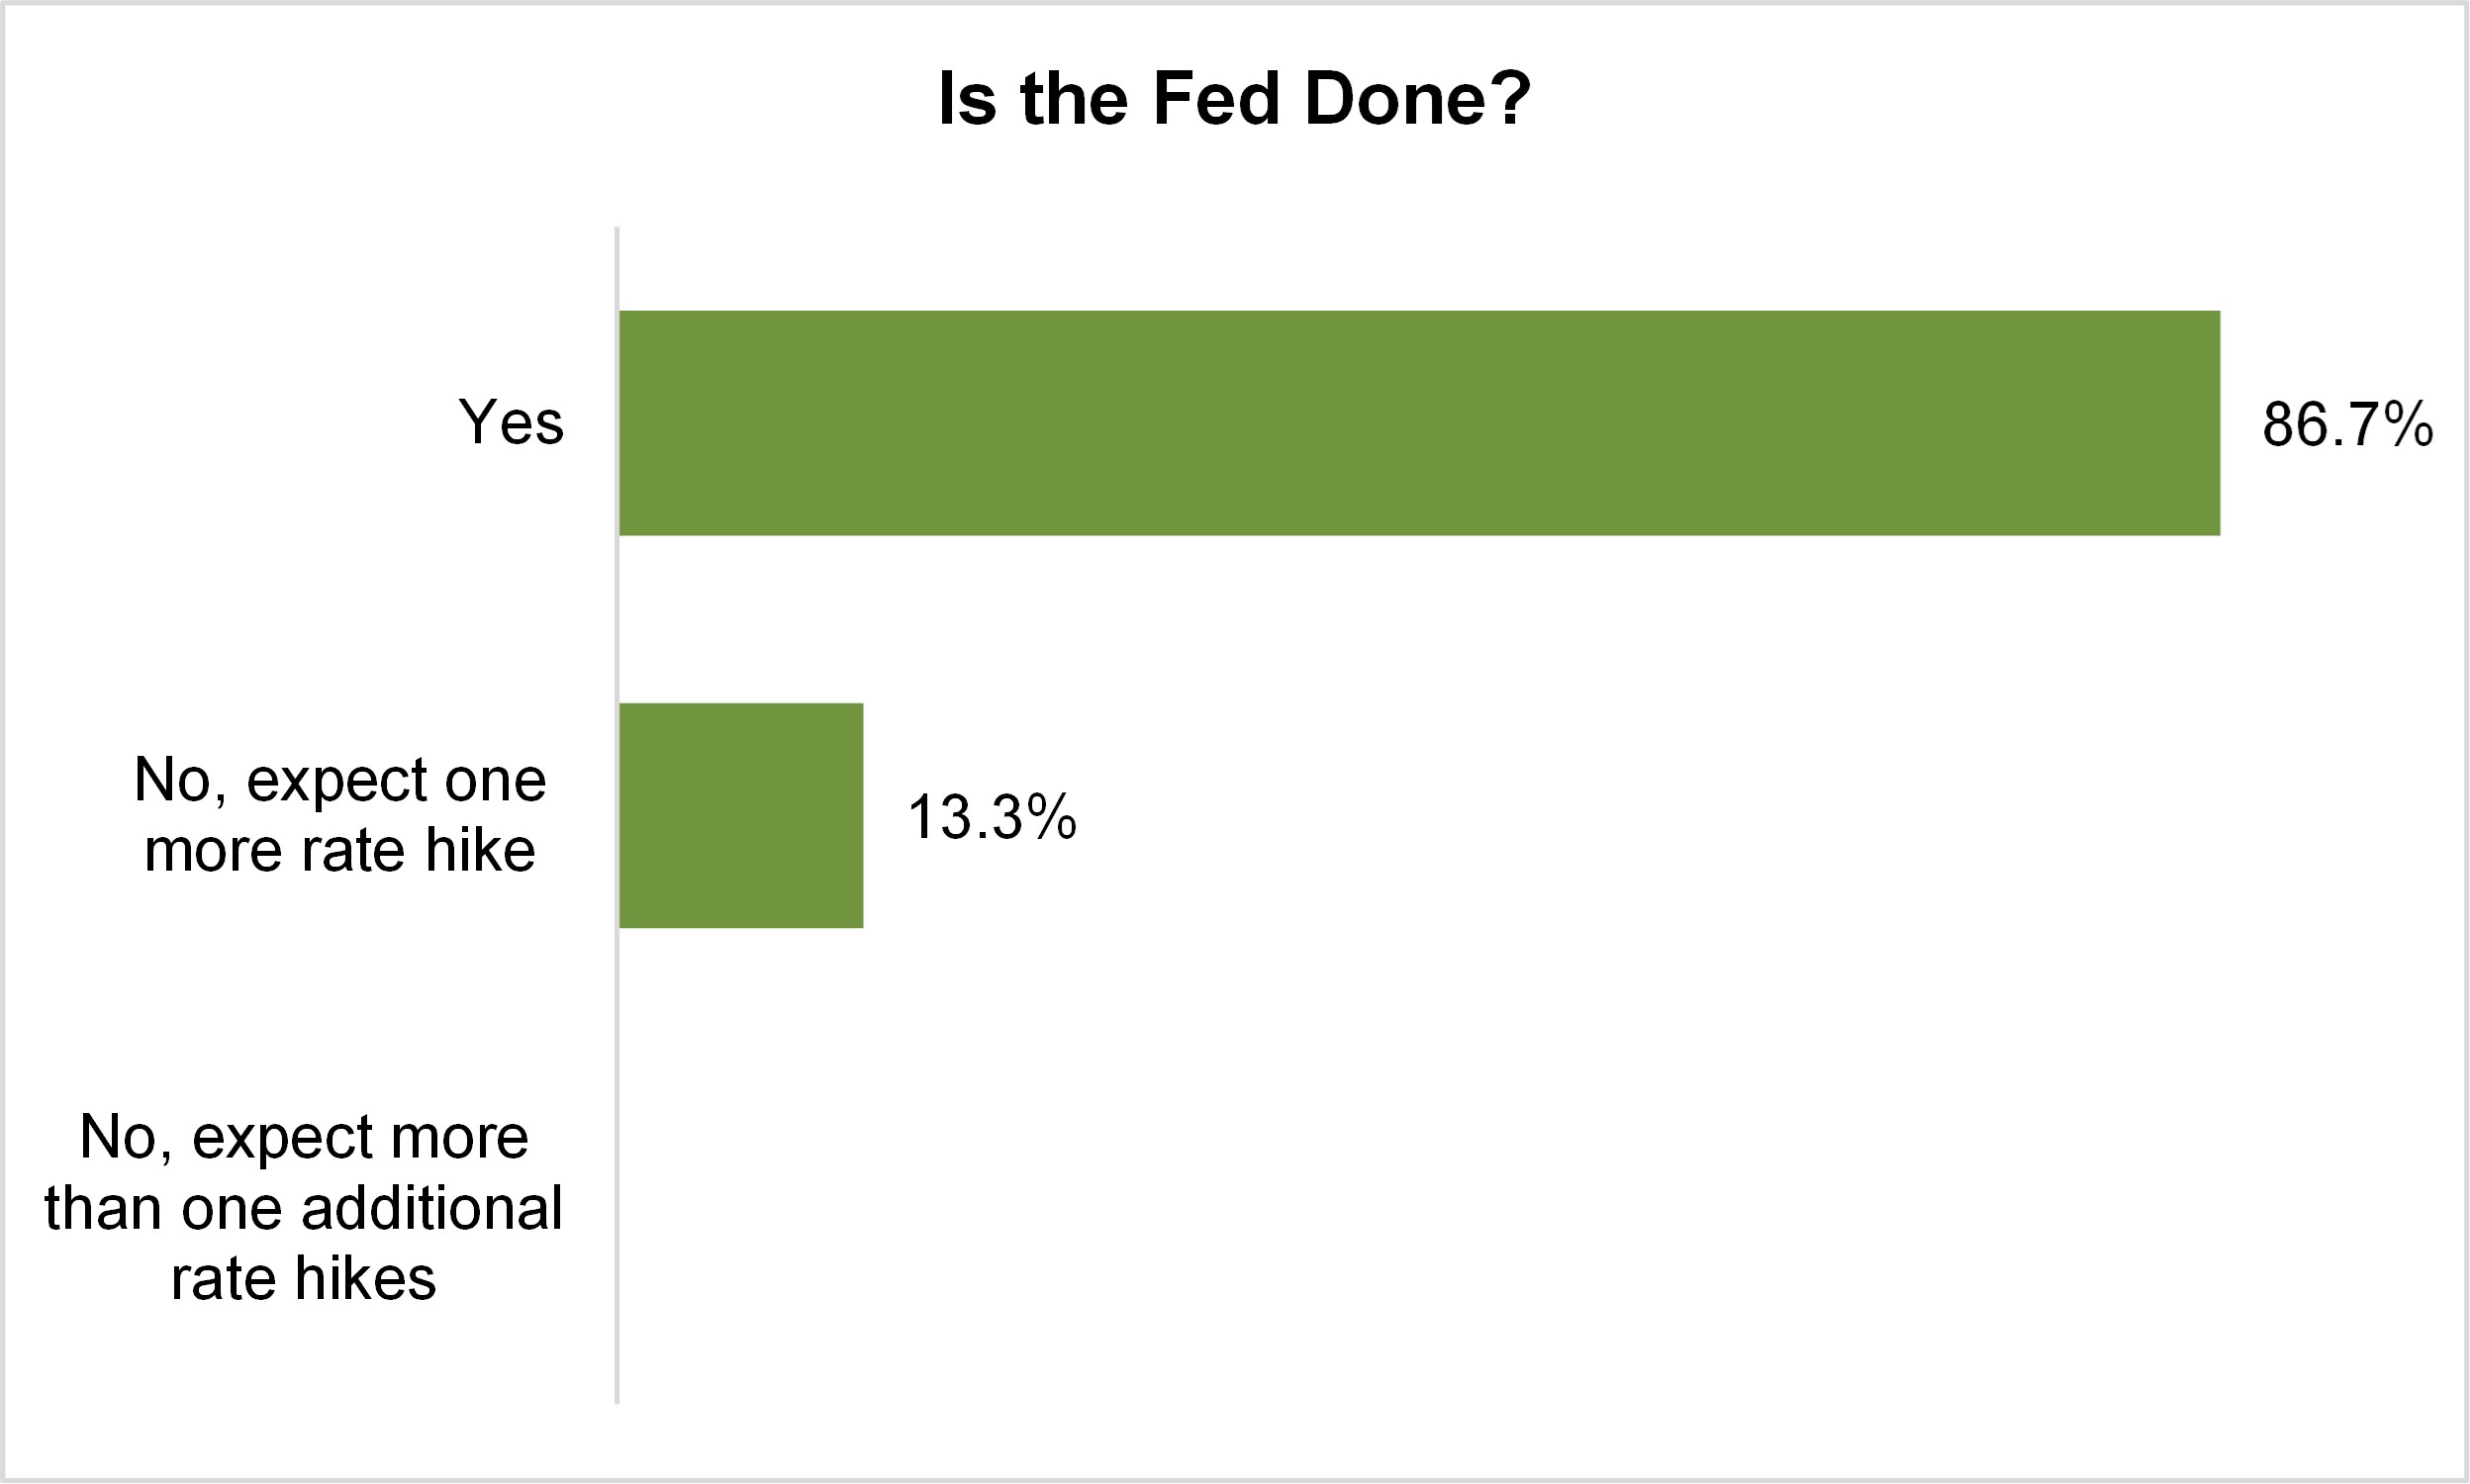
#3. As such, 86.7% of respondents believe the Fed is done with rate hikes. We note that markets have priced in a 97.7% probability of a pause at the December FOMC meeting (2.3% for another 25 bps hike) – that announcement comes tomorrow. Markets have priced in an 85.96% probability of a pause in January (12.1% for a 25 bps cut and 2.0% for a 25 bps hike).
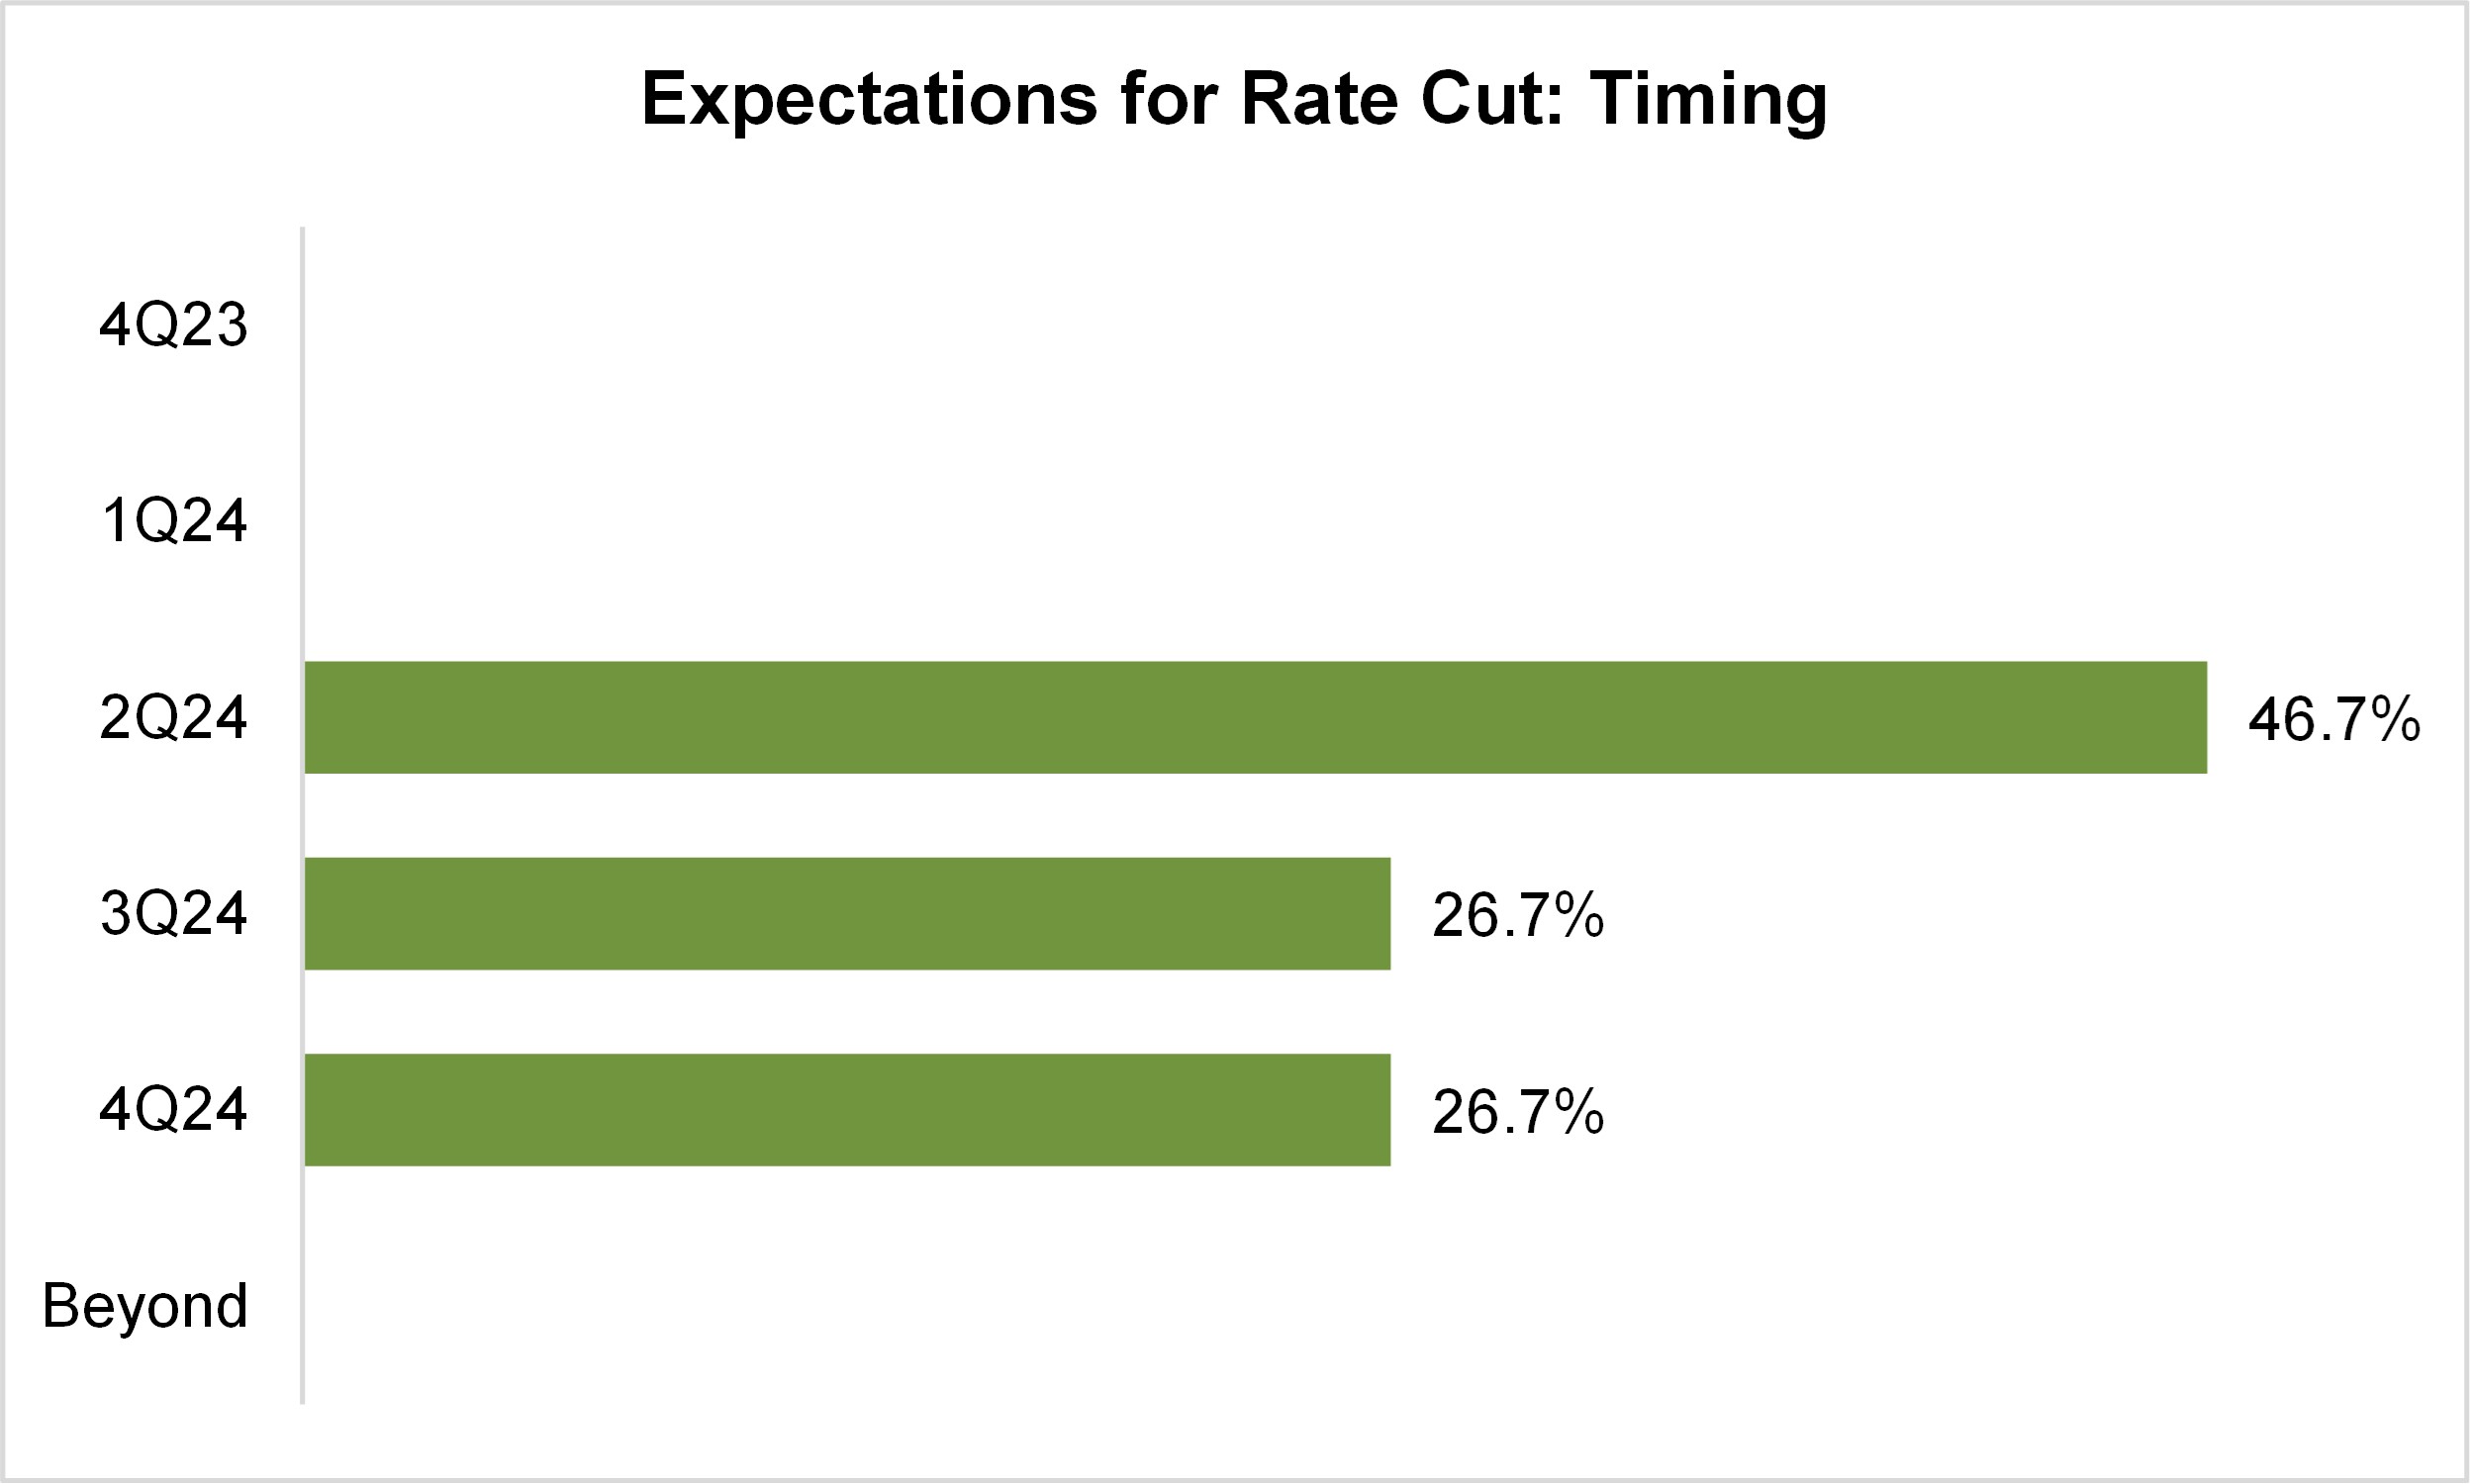
#4. Economists – and market participants – are now asking when will the Fed begin cutting rates? 46.7% of survey respondents expect the Fed to cut rates in 2Q24. The remaining responses were split across each of the quarters in the second half of the year, 26.7% each.
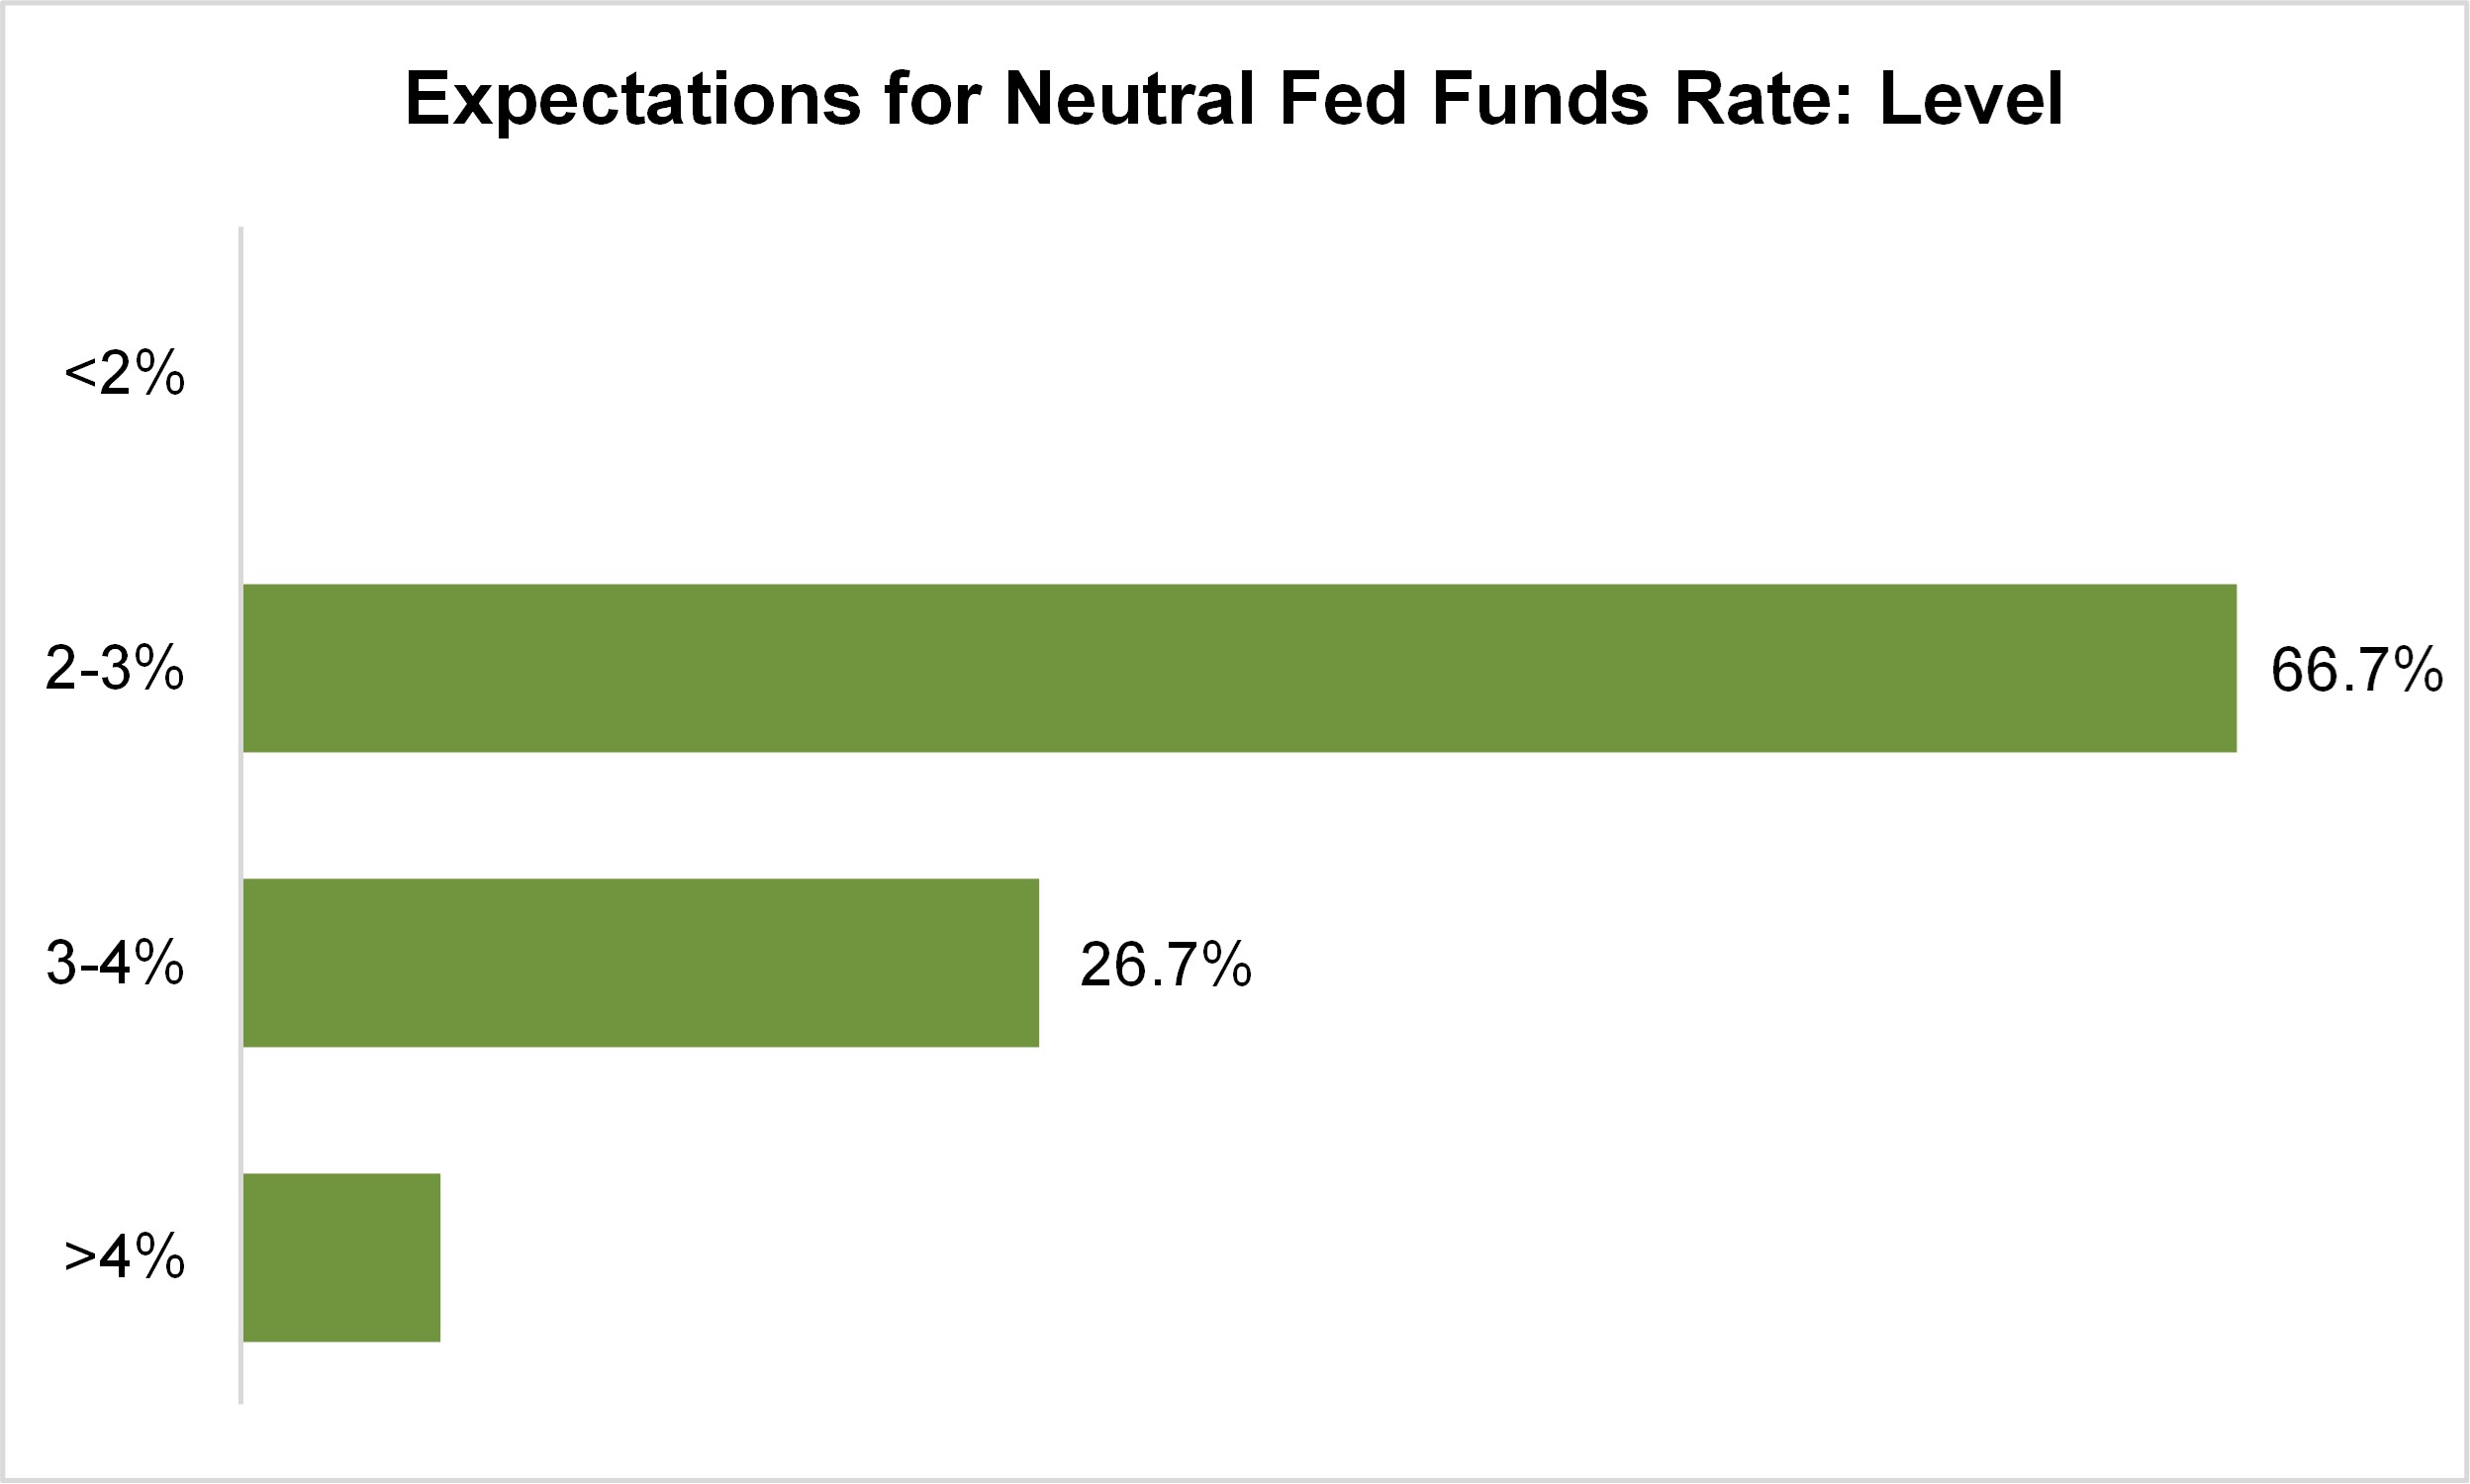
#5. Once the Fed begins cutting rates, 93.3% of respondents think it will take over 100 bps of cuts before stabilizing. What will be the final neutral Fed Funds rate? 66.7% of respondents estimate this rate will be 2-3%, to be achieved in 2026 (53.3% of respondents). Note: The survey was conducted between November 6-22.
—
Katie Kolchin, CFA, is Managing Director, Head of Research for SIFMA